← All bots

Discord application · Evidence

Johnny Alerts evidence

Effective September 19, 2026 · Last updated September 19, 2026

Inspect this bot’s workflow, identity and supporting records. Each example distinguishes retrieved messages, observed operation and illustrations.

01Workflow and supporting records

Bot identity and authorized use

Discord bot
Johnny Alerts
1507245396567785472
Attached analyst / source author
! Johnnylixf (I don't dm first)
196479731737034752
Sender channel
#johnny-sender
1496913223646187661
Authorized user observed using Send
! Johnnylixf (I don't dm first)
196479731737034752

The recorded component interaction was accepted for this user. The complete configured allowlist and rejection of unauthorized users have not been inspected.

Verified message records · 2026-09-19

Message Content lets the relay read the analyst’s original message and attachments before delivering it to configured channels. Sending the bot’s own output does not itself require that intent.

Source, preview and receipt were retrieved read-only through the bot on September 19, 2026. Reply references and component-interaction metadata connect the workflow. The matching destination message was also independently retrieved. Other destinations named in the receipt were not independently checked.

Reconstructed from real Discord messages, with the original text, timestamps and available images, except for explicitly labeled redactions. Layout is simplified; decorative or unavailable media may be omitted. These are website renderings, not screenshots of the Discord client. Source links require access to the channel.
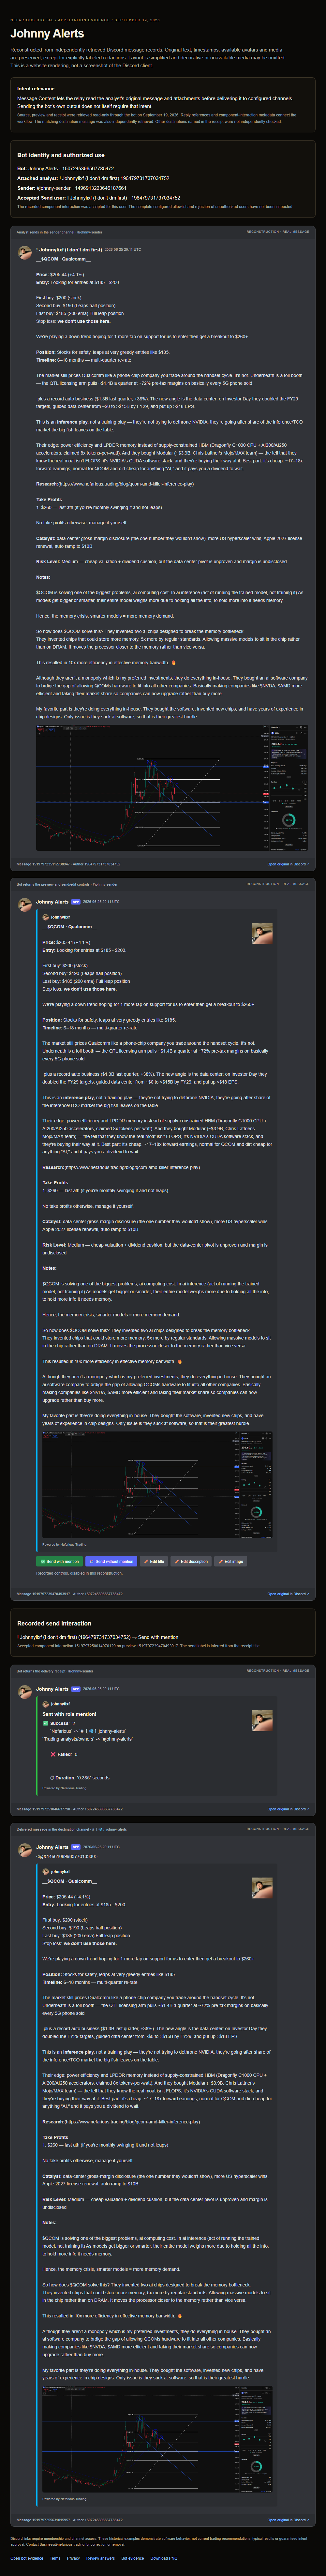
Watch the workflow

Reconstruction from real records · illustrative typing and timing · no live messages

#johnny-sender · ! Johnnylixf (I don't dm first)

Illustrative composition of the recorded source message

The saved Discord record proves the sent message, not the original keystrokes.

Step 1 of 6
Inspect all 4 original message records
Analyst sends in the sender channel · #johnny-senderReconstruction · real message
! Johnnylixf (I don't dm first) Discord avatar
! Johnnylixf (I don't dm first)
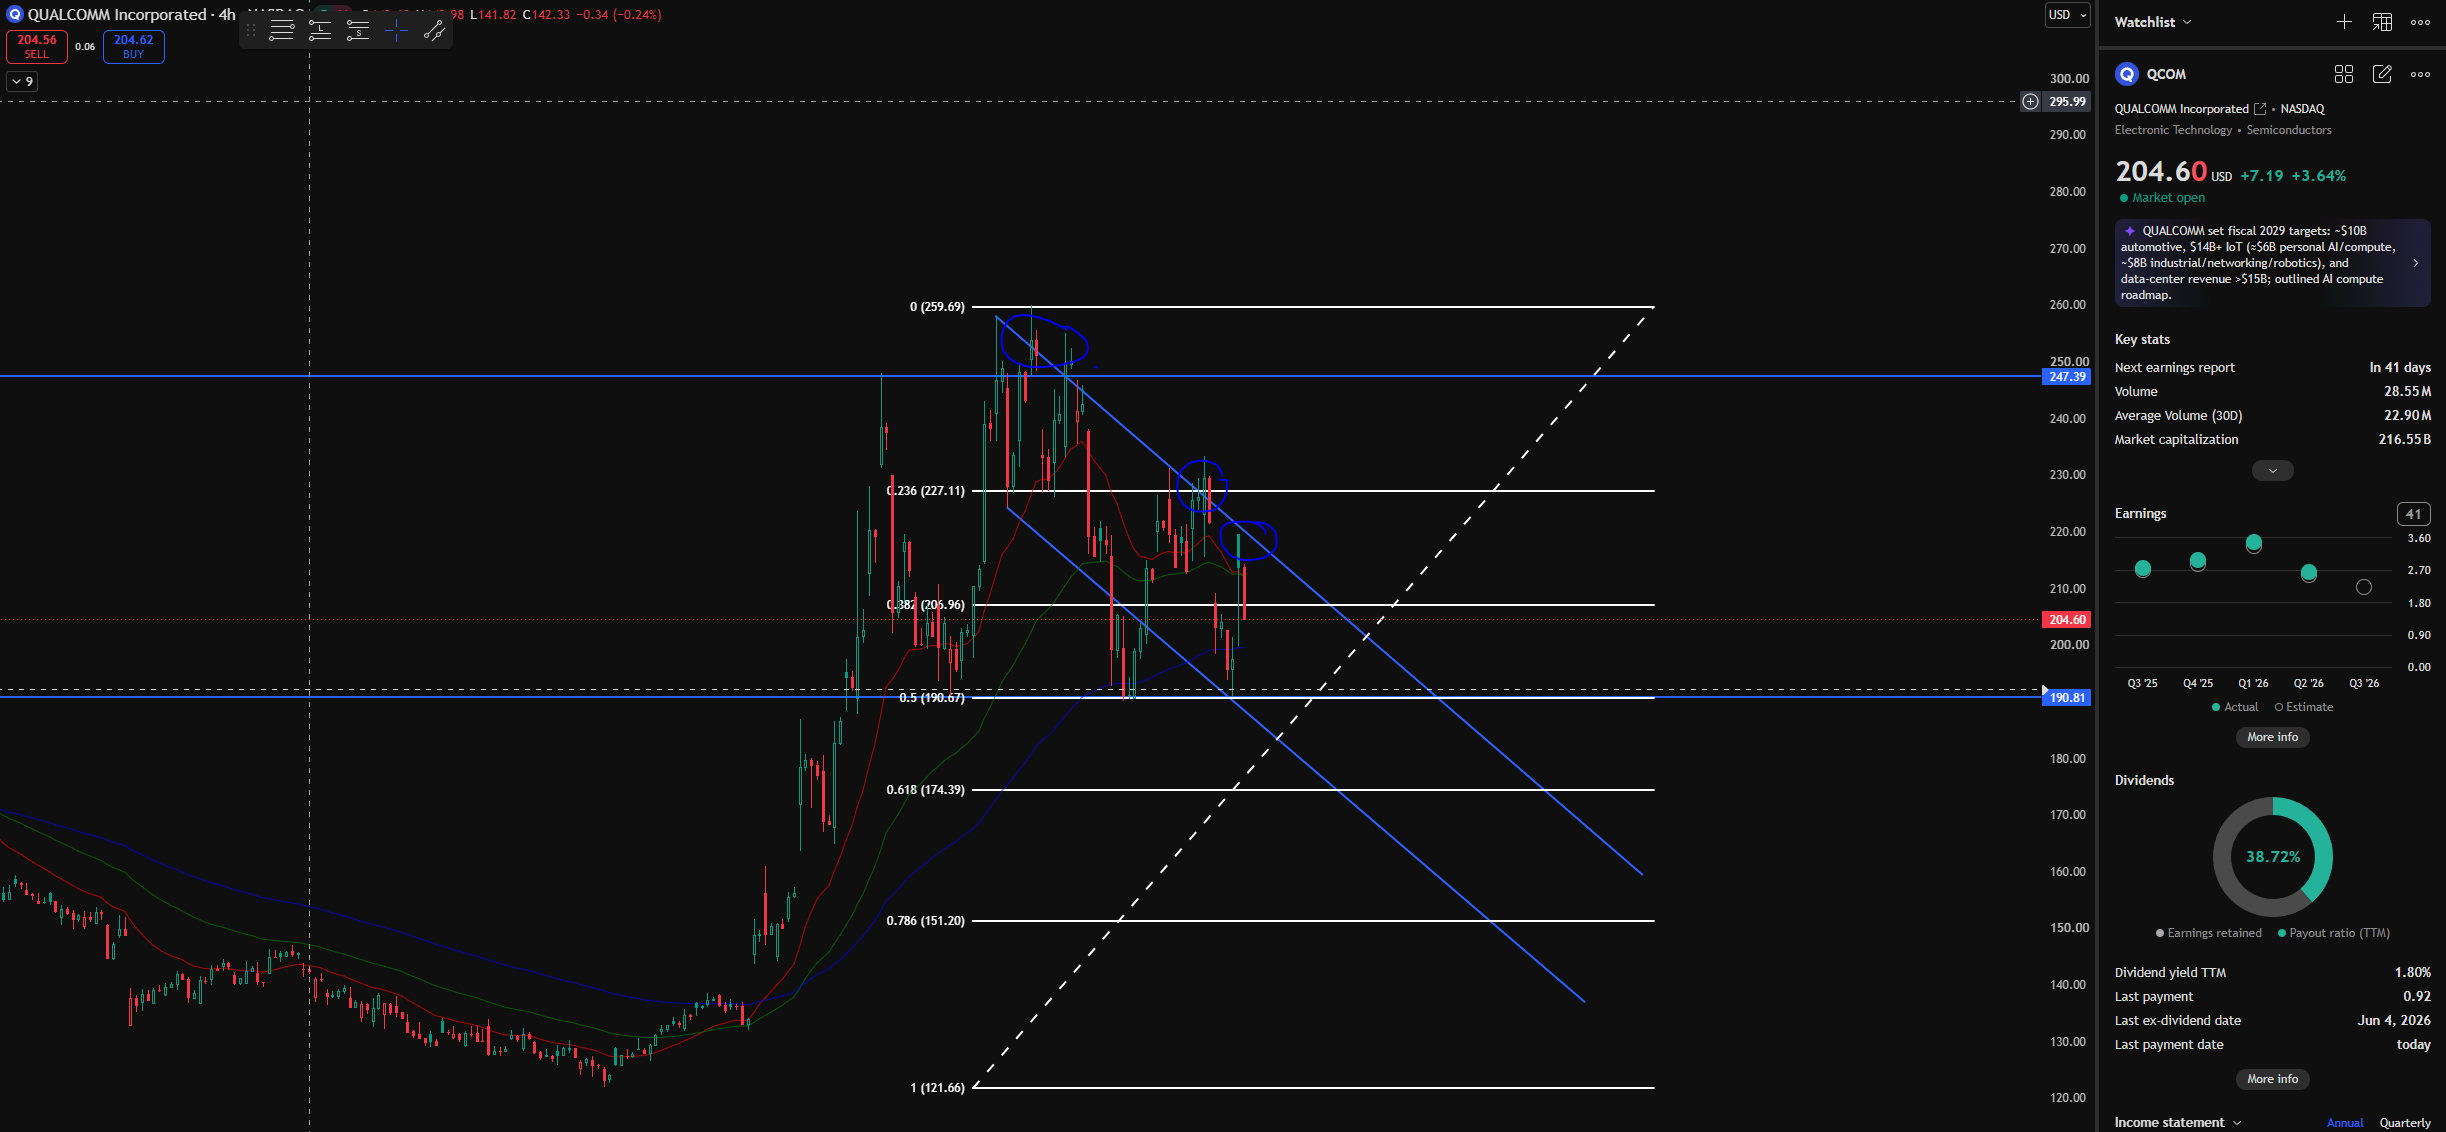
__$QCOM · Qualcomm__ Price: $205.44 (+4.1%) Entry: Looking for entries at $185 - $200. First buy: $200 (stock) Second buy: $190 (Leaps half position) Last buy: $185 (200 ema) Full leap position Stop loss: we don't use those here. We're playing a down trend hoping for 1 more tap on support for us to enter then get a breakout to $260+ Position: Stocks for safety, leaps at very greedy entries like $185. Timeline: 6–18 months — multi-quarter re-rate The market still prices Qualcomm like a phone-chip company you trade around the handset cycle. It's not. Underneath is a toll booth — the QTL licensing arm pulls ~$1.4B a quarter at ~72% pre-tax margins on basically every 5G phone sold plus a record auto business ($1.3B last quarter, +38%). The new angle is the data center: on Investor Day they doubled the FY29 targets, guided data center from ~$0 to >$15B by FY29, and put up >$18 EPS. This is an inference play, not a training play — they're not trying to dethrone NVIDIA, they're going after share of the inference/TCO market the big fish leaves on the table. Their edge: power efficiency and LPDDR memory instead of supply-constrained HBM (Dragonfly C1000 CPU + AI200/AI250 accelerators, claimed 8x tokens-per-watt). And they bought Modular (~$3.9B, Chris Lattner's Mojo/MAX team) — the tell that they know the real moat isn't FLOPS, it's NVIDIA's CUDA software stack, and they're buying their way at it. Best part: it's cheap. ~17–18x forward earnings, normal for QCOM and dirt cheap for anything "AI," and it pays you a dividend to wait. Research:(https://www.nefarious.trading/blog/qcom-amd-killer-inference-play) Take Profits 1. $260 — last ath (if you're monthly swinging it and not leaps) No take profits otherwise, manage it yourself. Catalyst: data-center gross-margin disclosure (the one number they wouldn't show), more US hyperscaler wins, Apple 2027 license renewal, auto ramp to $10B Risk Level: Medium — cheap valuation + dividend cushion, but the data-center pivot is unproven and margin is undisclosed Notes: $QCOM is solving one of the biggest problems, ai computing cost. In ai inference (act of running the trained model, not training it) As models get bigger or smarter, their entire model weighs more due to holding all the info, to hold more info it needs memory. Hence, the memory crisis, smarter models = more memory demand. So how does $QCOM solve this? They invented two ai chips designed to break the memory bottleneck. They invented chips that could store more memory, 5x more by regular standards. Allowing massive models to sit in the chip rather than on DRAM. It moves the processor closer to the memory rather than vice versa. This resulted in 10x more efficiency in effective memory banwidth. 🔥 Although they aren't a monopoly which is my preferred investments, they do everything in-house. They bought an ai software company to brdige the gap of allowing QCOMs hardware to fit into all other companies. Basically making companies like $NVDA, $AMD more efficient and taking their market share so companies can now upgrade rather than buy more. My favorite part is they're doing everything in-house. They bought the software, invented new chips, and have years of experience in chip designs. Only issue is they suck at software, so that is their greatest hurdle.
image.png
Message 1519797235112738947 · Author 196479731737034752Open original in Discord ↗
Bot returns the preview and send/edit controls · #johnny-senderReconstruction · real message
Johnny Alerts Discord avatar
Johnny AlertsAPP
johnnylixf
Original embed thumbnail
__$QCOM · Qualcomm__ Price: $205.44 (+4.1%) Entry: Looking for entries at $185 - $200. First buy: $200 (stock) Second buy: $190 (Leaps half position) Last buy: $185 (200 ema) Full leap position Stop loss: we don't use those here. We're playing a down trend hoping for 1 more tap on support for us to enter then get a breakout to $260+ Position: Stocks for safety, leaps at very greedy entries like $185. Timeline: 6–18 months — multi-quarter re-rate The market still prices Qualcomm like a phone-chip company you trade around the handset cycle. It's not. Underneath is a toll booth — the QTL licensing arm pulls ~$1.4B a quarter at ~72% pre-tax margins on basically every 5G phone sold plus a record auto business ($1.3B last quarter, +38%). The new angle is the data center: on Investor Day they doubled the FY29 targets, guided data center from ~$0 to >$15B by FY29, and put up >$18 EPS. This is an inference play, not a training play — they're not trying to dethrone NVIDIA, they're going after share of the inference/TCO market the big fish leaves on the table. Their edge: power efficiency and LPDDR memory instead of supply-constrained HBM (Dragonfly C1000 CPU + AI200/AI250 accelerators, claimed 8x tokens-per-watt). And they bought Modular (~$3.9B, Chris Lattner's Mojo/MAX team) — the tell that they know the real moat isn't FLOPS, it's NVIDIA's CUDA software stack, and they're buying their way at it. Best part: it's cheap. ~17–18x forward earnings, normal for QCOM and dirt cheap for anything "AI," and it pays you a dividend to wait. Research:(https://www.nefarious.trading/blog/qcom-amd-killer-inference-play) Take Profits 1. $260 — last ath (if you're monthly swinging it and not leaps) No take profits otherwise, manage it yourself. Catalyst: data-center gross-margin disclosure (the one number they wouldn't show), more US hyperscaler wins, Apple 2027 license renewal, auto ramp to $10B Risk Level: Medium — cheap valuation + dividend cushion, but the data-center pivot is unproven and margin is undisclosed Notes: $QCOM is solving one of the biggest problems, ai computing cost. In ai inference (act of running the trained model, not training it) As models get bigger or smarter, their entire model weighs more due to holding all the info, to hold more info it needs memory. Hence, the memory crisis, smarter models = more memory demand. So how does $QCOM solve this? They invented two ai chips designed to break the memory bottleneck. They invented chips that could store more memory, 5x more by regular standards. Allowing massive models to sit in the chip rather than on DRAM. It moves the processor closer to the memory rather than vice versa. This resulted in 10x more efficiency in effective memory banwidth. 🔥 Although they aren't a monopoly which is my preferred investments, they do everything in-house. They bought an ai software company to brdige the gap of allowing QCOMs hardware to fit into all other companies. Basically making companies like $NVDA, $AMD more efficient and taking their market share so companies can now upgrade rather than buy more. My favorite part is they're doing everything in-house. They bought the software, invented new chips, and have years of experience in chip designs. Only issue is they suck at software, so that is their greatest hurdle.
Original image attached to Johnny Alerts's message

Powered by Nefarious.Trading

Recorded controls, disabled in this reconstruction.

Message 1519797239470493917 · Author 1507245396567785472Open original in Discord ↗
Bot returns the delivery receipt · #johnny-senderReconstruction · real message
Johnny Alerts Discord avatar
Johnny AlertsAPP
johnnylixf
Original embed thumbnail

Sent with role mention!

✅ Success: `2` `Nefarious` -> `#〔❄️〕johnny-alerts` `Trading analysts/owners` -> `#johnny-alerts` ❌ Failed: `0` ⏱ Duration: `0.385` seconds

Powered by Nefarious.Trading

Message 1519797251046637790 · Author 1507245396567785472Open original in Discord ↗
Delivered message in the destination channel · #〔❄️〕johnny-alertsReconstruction · real message
Johnny Alerts Discord avatar
Johnny AlertsAPP
@role
johnnylixf
Original embed thumbnail
__$QCOM · Qualcomm__ Price: $205.44 (+4.1%) Entry: Looking for entries at $185 - $200. First buy: $200 (stock) Second buy: $190 (Leaps half position) Last buy: $185 (200 ema) Full leap position Stop loss: we don't use those here. We're playing a down trend hoping for 1 more tap on support for us to enter then get a breakout to $260+ Position: Stocks for safety, leaps at very greedy entries like $185. Timeline: 6–18 months — multi-quarter re-rate The market still prices Qualcomm like a phone-chip company you trade around the handset cycle. It's not. Underneath is a toll booth — the QTL licensing arm pulls ~$1.4B a quarter at ~72% pre-tax margins on basically every 5G phone sold plus a record auto business ($1.3B last quarter, +38%). The new angle is the data center: on Investor Day they doubled the FY29 targets, guided data center from ~$0 to >$15B by FY29, and put up >$18 EPS. This is an inference play, not a training play — they're not trying to dethrone NVIDIA, they're going after share of the inference/TCO market the big fish leaves on the table. Their edge: power efficiency and LPDDR memory instead of supply-constrained HBM (Dragonfly C1000 CPU + AI200/AI250 accelerators, claimed 8x tokens-per-watt). And they bought Modular (~$3.9B, Chris Lattner's Mojo/MAX team) — the tell that they know the real moat isn't FLOPS, it's NVIDIA's CUDA software stack, and they're buying their way at it. Best part: it's cheap. ~17–18x forward earnings, normal for QCOM and dirt cheap for anything "AI," and it pays you a dividend to wait. Research:(https://www.nefarious.trading/blog/qcom-amd-killer-inference-play) Take Profits 1. $260 — last ath (if you're monthly swinging it and not leaps) No take profits otherwise, manage it yourself. Catalyst: data-center gross-margin disclosure (the one number they wouldn't show), more US hyperscaler wins, Apple 2027 license renewal, auto ramp to $10B Risk Level: Medium — cheap valuation + dividend cushion, but the data-center pivot is unproven and margin is undisclosed Notes: $QCOM is solving one of the biggest problems, ai computing cost. In ai inference (act of running the trained model, not training it) As models get bigger or smarter, their entire model weighs more due to holding all the info, to hold more info it needs memory. Hence, the memory crisis, smarter models = more memory demand. So how does $QCOM solve this? They invented two ai chips designed to break the memory bottleneck. They invented chips that could store more memory, 5x more by regular standards. Allowing massive models to sit in the chip rather than on DRAM. It moves the processor closer to the memory rather than vice versa. This resulted in 10x more efficiency in effective memory banwidth. 🔥 Although they aren't a monopoly which is my preferred investments, they do everything in-house. They bought an ai software company to brdige the gap of allowing QCOMs hardware to fit into all other companies. Basically making companies like $NVDA, $AMD more efficient and taking their market share so companies can now upgrade rather than buy more. My favorite part is they're doing everything in-house. They bought the software, invented new chips, and have years of experience in chip designs. Only issue is they suck at software, so that is their greatest hurdle.
Original image attached to Johnny Alerts's message

Powered by Nefarious.Trading

Message 1519797255631015957 · Author 1507245396567785472Open original in Discord ↗

02Public evidence and removal

These selected examples are public, including any displayed Discord IDs, messages, timestamps, avatars, media and aggregate operational results. Visitors do not need access to the original channel. Credentials, private trading account details and raw message archives are excluded.

Evidence files and deployment copies have no automatic 30-day expiry. Email Business@nefarious.trading with this bot’s name and the relevant example to request correction or removal. Removal must address active pages, downloads, cached media and retained copies under our control. Evidence is not used to train AI models.